The Problem
Holding other people’s money, by law
NDEMNIFLY is an independent aviation insurance brokerage serving clients nationwide. If it flies or sits on an airport, David Asman can insure it: owner-flown aircraft, student pilots renting planes, hangars, maintenance shops, the fuel trucks driving around the ramp.
David is a chemistry major who owns a restaurant and flies his own planes, so insurance was never the plan. It started at a barbecue, in a conversation with the broker who had written his restaurant’s commercial policy. David was a frustrated customer with a lot of questions, and the answers were interesting enough that he went and got licensed himself. Aviation was the part he already knew firsthand, and he built that desk inside a small property and casualty agency. When the agency sold to buyers with no interest in aviation, he took the book and started NDEMNIFLY on his own.
Aviation insurance runs on a model most people don’t encounter. Home and auto policies are direct bill, where the customer pays the carrier and the carrier pays the agency a commission. Aviation is agency bill. The client pays David, David remits the net premium to the carrier, and his commission is what stays behind.
That makes him a fiduciary holding someone else’s money, and the rules around it are strict.
I’m holding money as somebody’s fiduciary to then remit when it’s called due by the carrier. Every state regulates it a little differently. Whose money is it, what can be collected and earned on it. But the general gist is it’s got to be auditable and there can’t be a commingling of funds.
David Asman, Founder
Early on, before he had terms with carriers, the money also had to move fast.
You’re buying a plane today, you need coverage today. I can’t wait on anything.
David Asman, Founder
ACH could take a week. Cards settled in a day or two, but the processing fee came out of a commission he had not collected yet. In these situations the client had already paid. What held things up was clearing time: until the payment finished settling into David’s account, there was nothing for him to send the carrier.
There would be a situation where I want to sell this $20,000 policy, but I don’t have the $17,000 ready to go to pay for it.
David Asman, Founder
That particular squeeze eased on its own. The agency grew, the credibility came with it, and David now has 30 to 60 day net terms across the board, which took cash flow off the table. What growth could not fix was where the money sat once it arrived.
David runs his books on the Profit First method, which means money gets allocated across dedicated accounts twice a month: operating expenses, owner’s compensation, profit, taxes. His previous bank only paid interest on savings accounts, and savings accounts cap how many transfers they will accept. The account structure his compliance required and the account structure that earned anything were not the same thing.
The Solution
A trust account that earns
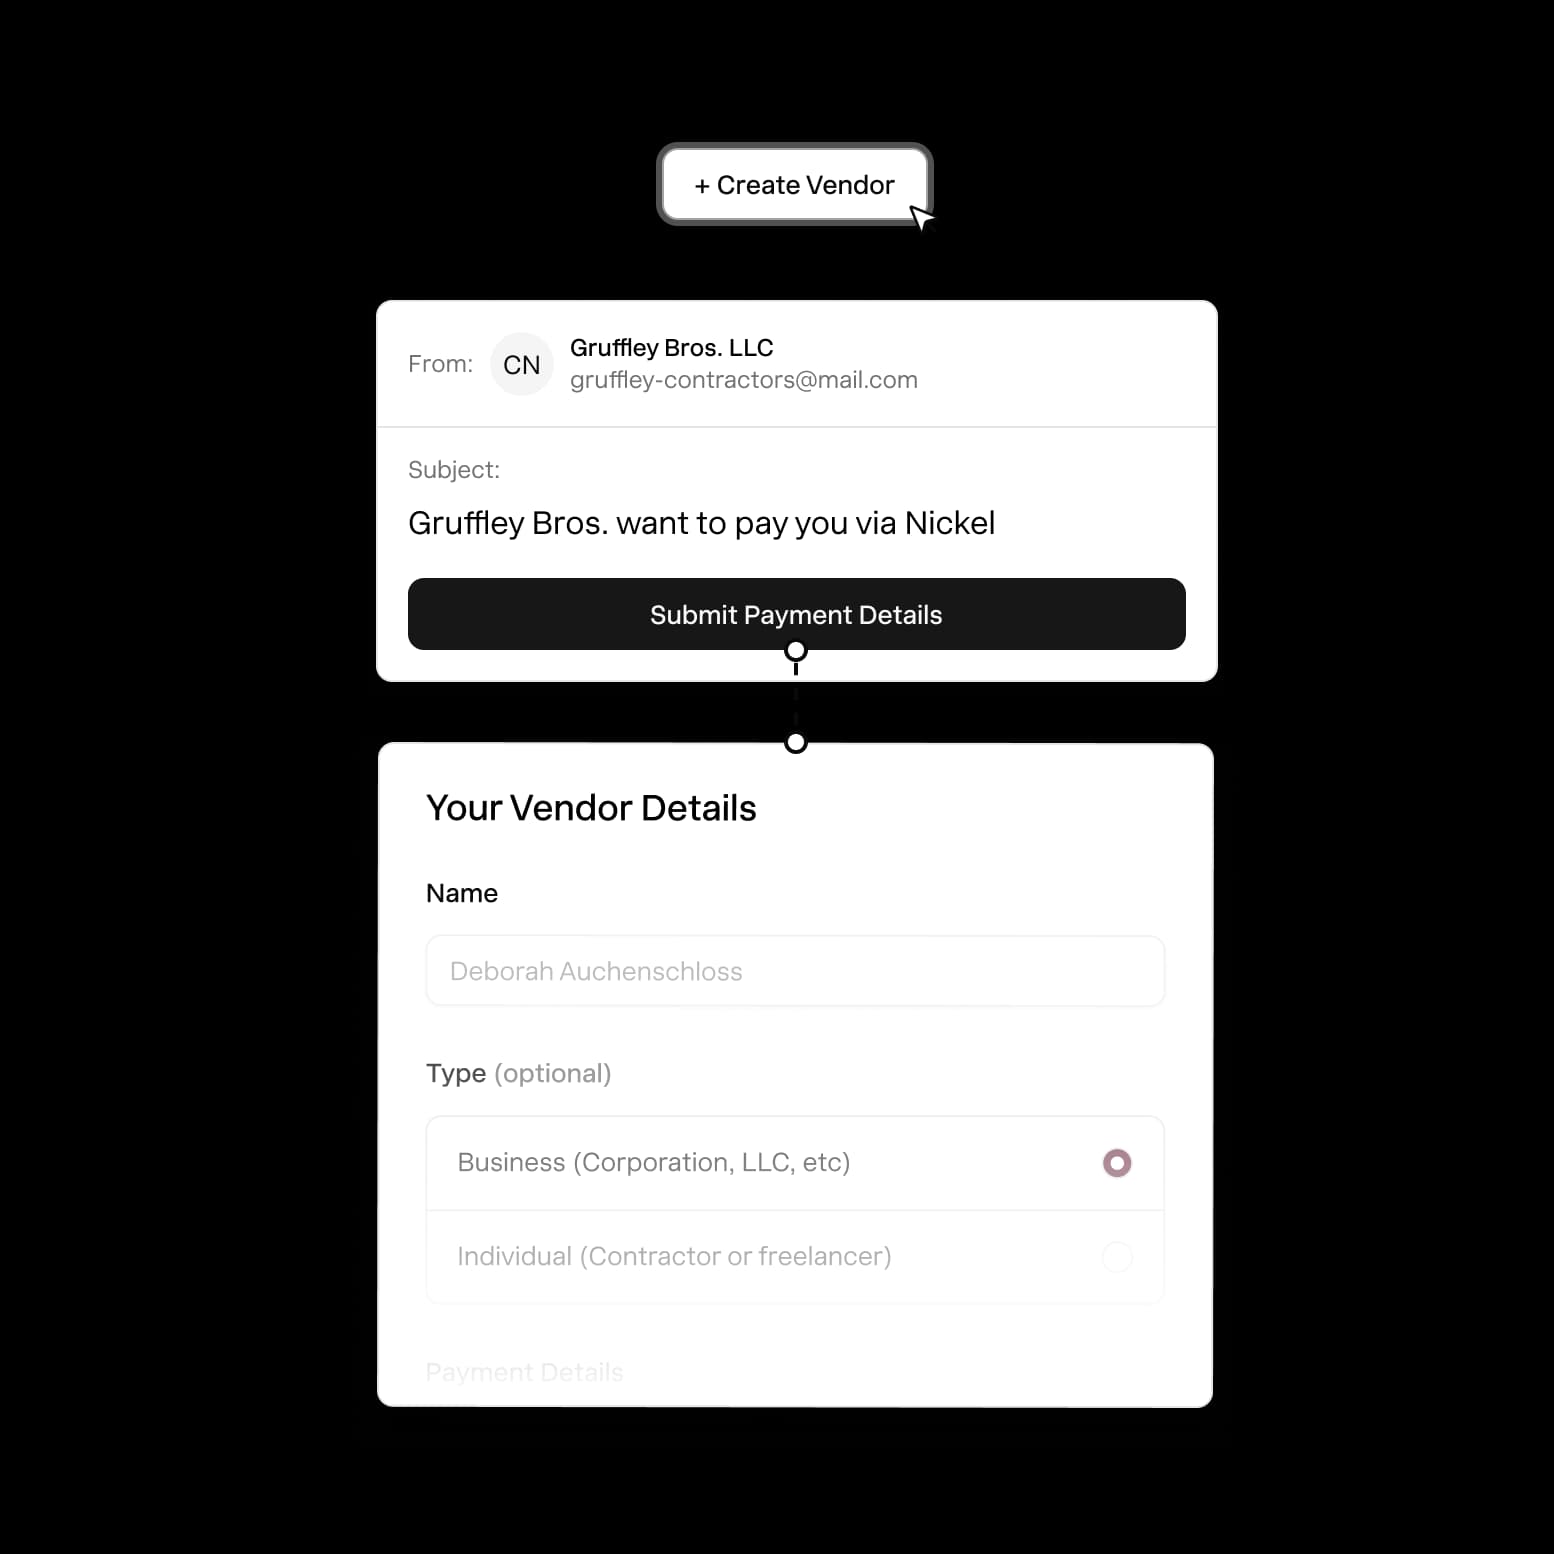
Nickel came in first on the invoicing side, about twenty months ago, replacing a platform that was slow to run and expensive to use. What David wanted was a payment flow built for the way an agency actually bills.
Nickel handled my agency billed payment flow better than what Helcim made available. It was also less expensive and offers faster settlement.
David Asman, Founder
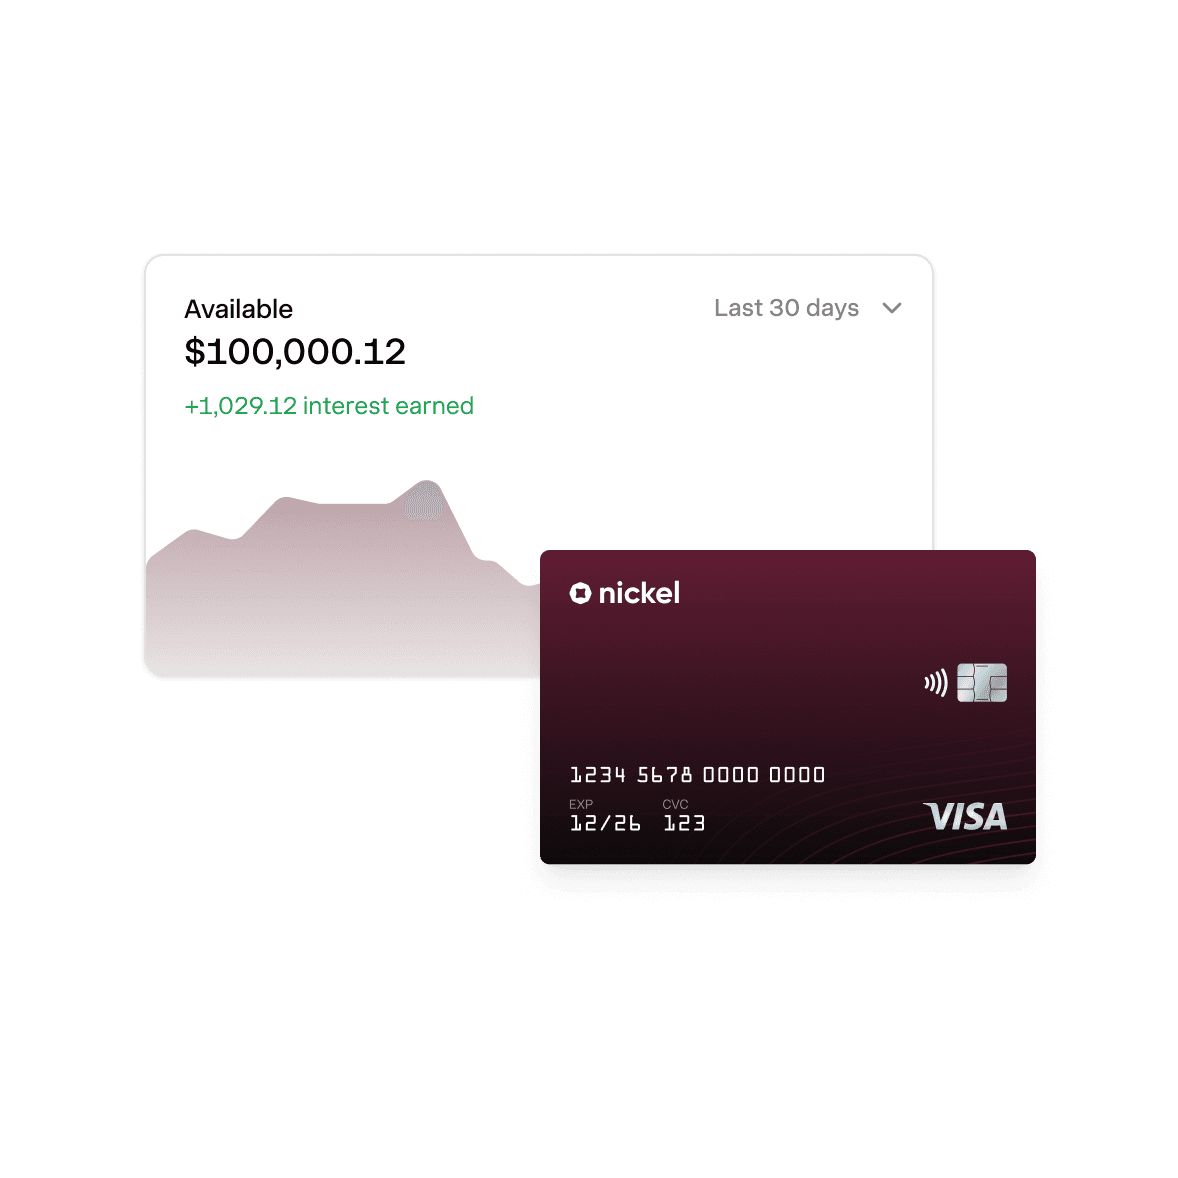
Then David opened two Nickel Banking accounts. Premiums land in the first trust account at full value, and he sweeps his commissions and agency fees into the second one.
The separation is the part regulators require. The interest earned is the part he did not expect to have.
Being solo shapes what he weighs. David works out of his house, travels constantly to reach clients, and runs the entire agency from a laptop.
My office is basically anywhere I have this. I’m in 48 states, I have clients, I’m traveling, I’m on the move, and I’m solo. I need speed.
David Asman, Founder
Consolidating usually costs a one man shop something. This time it came with a better rate than he was already getting.
A trust balance is not the agency’s money to spend. Premiums move out to carriers when they come due and earned commissions move over to the operating side, but putting any of it toward unrelated business expenses is off limits, and commingling funds is a serious violation. For as long as David has been in the business, whatever sat in that account between those movements earned nothing.
There’s over $200 of interest accrued since opening those accounts. While 200 bucks isn’t game changing, it’s $200 that didn’t exist. It’s a found $200. And the cost of putting that 200 bucks in my pocket is a convenience to the business rather than a detriment to other process. That’s a win across the board.
David Asman, Founder
That is seven weeks of accrual on balances he was already holding, with nothing changing about how he holds them.
Between invoicing and banking, both directions of NDEMNIFLY’s money now run through one platform. Support has come up rarely, and David says that when it has, it has been responsive and quick to resolve.
It’s been great. I have used several similar services and so far Nickel has been my favorite. It’s easy, fast, reliable, and at nearly no cost to my business.
David Asman, Founder
NDEMNIFLY has grown substantially over the past two years, enough that David is now looking to bring on producers.
I’m not coming from a legacy model of insurance agency. I’m coming from, how can I make this better for people like me? There are ways to disrupt some of these antiquated models and systems, and Nickel’s been a part of that for NDEMNIFLY.
David Asman, Founder
For now he is still the whole agency, and the money moving through it no longer sits still on its way to the carrier.